Different groups have different people, budgets and priorities.
A company may want basic life protection for its employees. An association may want to add accident benefits. Another organization may be concerned about critical illness, disability or hospitalization.
Group Yearly Renewable Term — GYRT — provides a flexible foundation from which a group protection program can be built.
GYRT is structured as one-year renewable group term life insurance, normally arranged by an organization for eligible members or employees. The core benefit provides life protection, with benefits payable to the applicable beneficiaries if a covered member dies while insured.
Begin with the foundation
Life protection
At its simplest, GYRT provides a death benefit for covered members. That gives the family an immediate financial resource if the insured member dies during the coverage period.
Because the protection is arranged for a group, meaningful basic coverage may be made available at a relatively modest cost.
An example
For illustration, a group arrangement might provide:
₱100,000 life insurance coverage
for an annual premium of approximately:
₱600 per covered member per year
This is only an example, not a published quotation or promise of pricing.
Actual premiums depend on factors such as the group's census, ages, occupations, benefit amounts, eligibility and underwriting requirements.
The point of the example is simply to show why group life protection can be worth exploring: a relatively small group cost can potentially provide meaningful immediate protection to a member's family.
Build around the group
Protection can be assembled from building blocks. Basic life insurance doesn't have to be the entire program. Depending on the group's requirements and the available program, additional benefits can be added as riders.
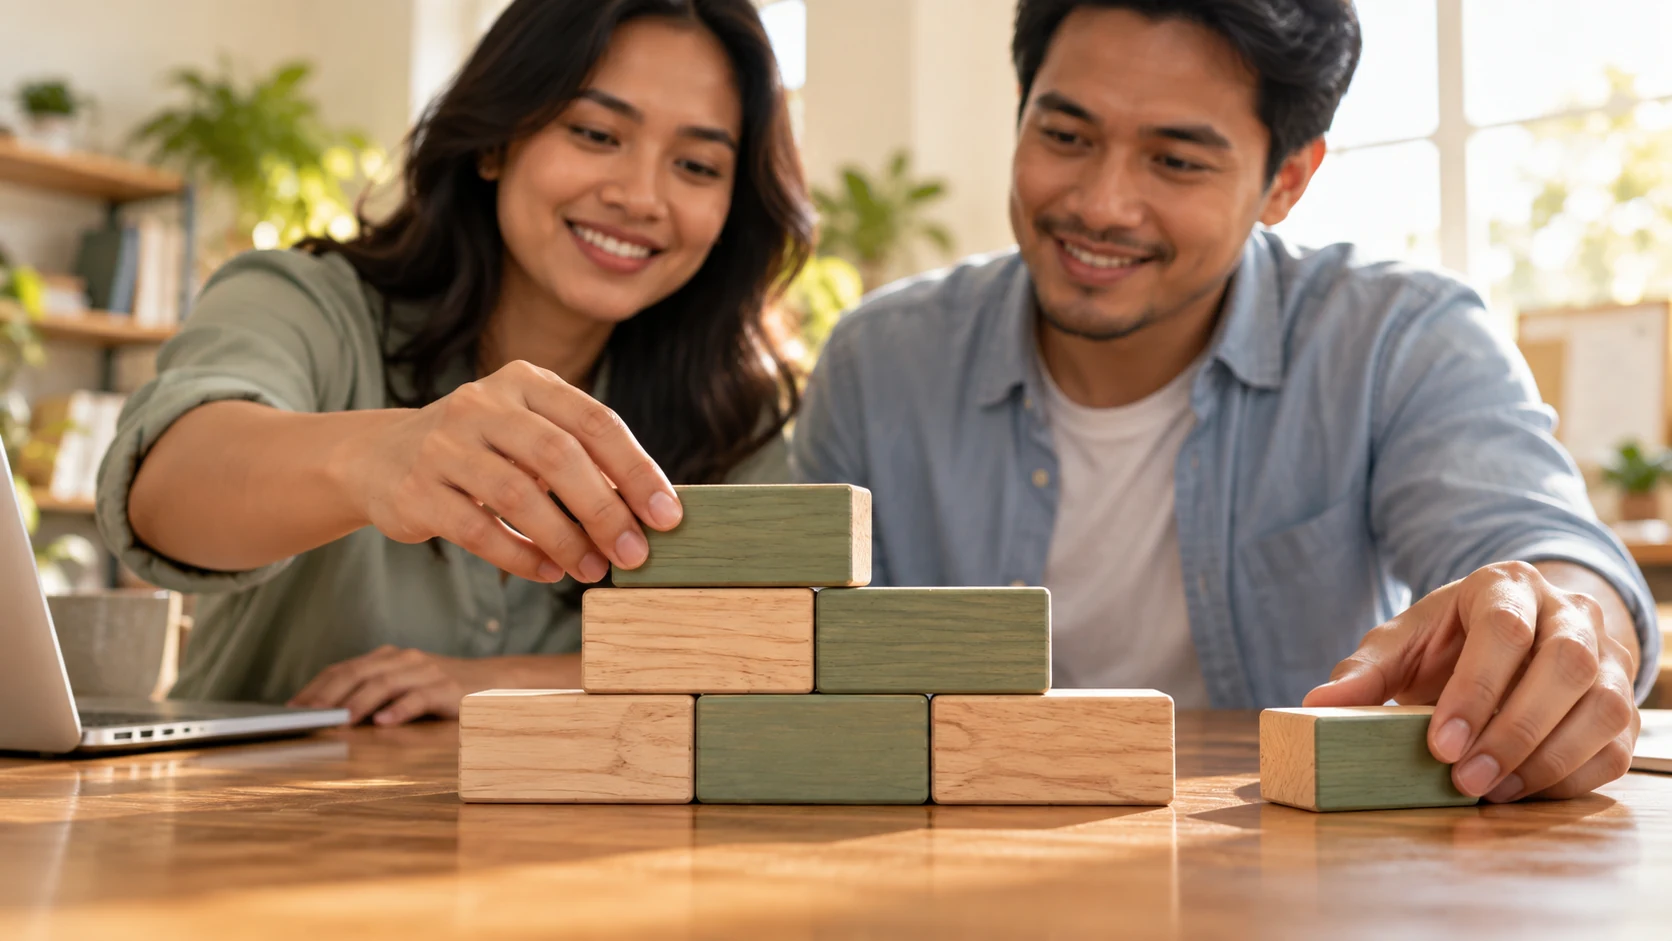
Available building blocks
- Terminal Illness
- Total and Permanent Disability
- Accidental Death & Dismemberment
- Accident Medical Reimbursement
- Critical Illness
- Hospital Daily Income
- Burial Benefit
Build for the need
One organization might decide: Life Protection + Accident Protection.
Another: Life Protection + Critical Illness + Disability.
Another may want a broader package.
The group doesn't have to buy everything. That's the advantage of thinking in building blocks.
The question isn't: Which standard package should we buy?
A better question is: What protection would be most useful to our people, and what can the group reasonably provide?
The selected benefits can then be built around those priorities, subject to the applicable product, eligibility and underwriting rules.
Why yearly renewable protection?
The needs of a group can change. People join. People leave. The age profile changes. Budgets change. Organizational priorities change.
A yearly renewable structure gives the organization an opportunity to periodically review its group protection rather than assuming today's program will always be the right one. Renewal and future terms remain subject to the applicable group insurance arrangement.
Who might consider GYRT?
GYRT can potentially be relevant to companies and employers, government organizations, associations, cooperatives, unions and other eligible organized groups.
The exact structure depends on the organization and the people being protected.
A little protection across many people can matter.
For an organization, the annual cost of basic protection may look small. For the family that actually needs the benefit, it may not feel small at all.
That's the value of group protection: many people preparing together.
Want your organization to know more?
Group coverage is arranged with organizational leadership.
If you think GYRT may be useful to a group you belong to, we can explain the available building blocks and how group coverage works.
Learn more →The ₱600 annual premium for ₱100,000 life coverage is an example only and is not a quotation. Actual coverage, premiums, eligibility, riders and underwriting requirements depend on the applicable group arrangement.