The Kaiser Journey

You don't know which tomorrow will come.

That's why you prepare for more than one.

At 25, you're healthy, working and building your future.

Healthcare may not feel urgent yet.

But over the next 35 years, life can take many different turns.

You may need healthcare.

Your family may need protection.

Or you may stay healthy, reach retirement and discover that healthcare matters more than ever.

Follow one illustrated K100 journey from age 25 to age 60.

Follow the Journey ↓
Age 25→Age 32→Age 45→Age 60
A Filipino man through four stages of life: young professional, young father, mature professional and active older adult.

Illustrations on this page use historical K100 Blueprint assumptions. Projected values are not guaranteed and assume unused health benefits unless otherwise stated.

Chapter 1 — Age 25

Start while healthcare feels far away.

At 25, you may be more concerned about building a career, starting a family, buying a home or enjoying life.

That's normal.

But there's an advantage to preparing for long-term healthcare when you're young: time.

Suppose a 25-year-old starts a Kaiser Ultimate K100 plan.

Under the historical Blueprint illustration, K100 was designed around three parts of a financial foundation:

  • Protect yourself — Long-Term Healthcare
  • Protect your family — Life Insurance
  • Protect your future — Long-Term accumulation

The Blueprint describes K100 as a 7-pay long-term healthcare plan that matures after 20 years and includes term life insurance and consumable healthcare benefits along the way.

During the first seven years

The member pays the plan while healthcare protection is already available subject to the plan's terms.

The historical K100 Blueprint lists:

₱58,821 annual installment
or ₱5,882 monthly

together with a ₱60,000 annual hospitalization benefit limit, annual physical examination, dental prophylaxis and dental benefits during the accumulation period.

But the important point isn't simply the list of benefits.

The journey has already begun.

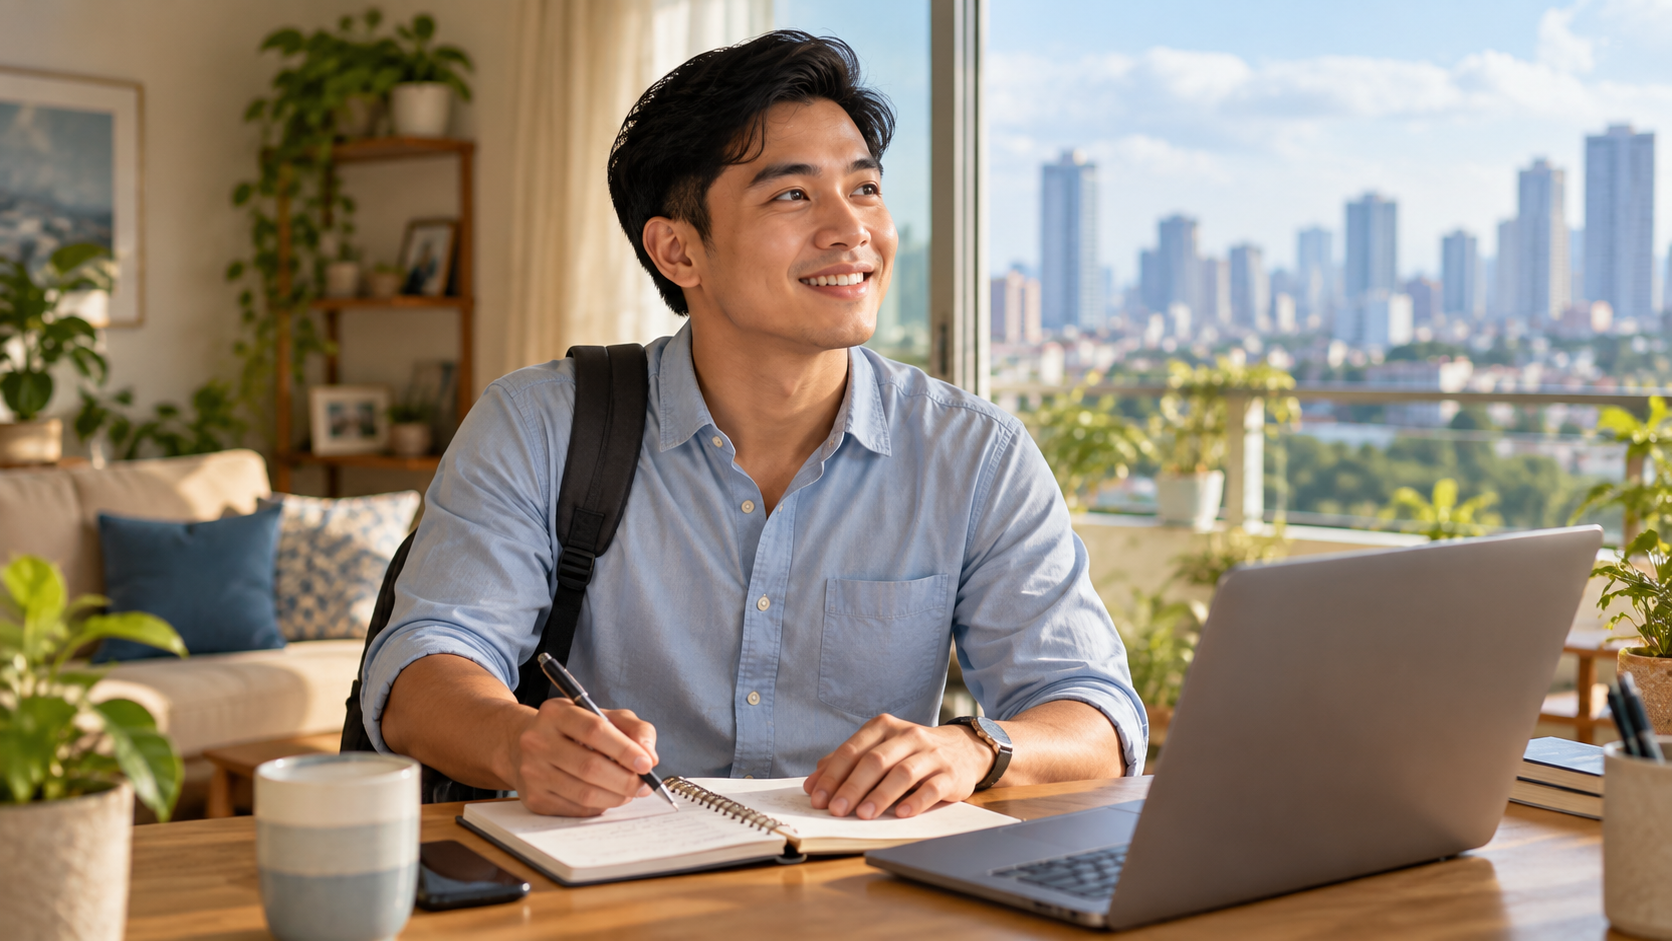
Young Filipino professional beginning adult life in a bright workspace.
Filipino father spending time with his wife and young daughter at home.
Chapter 2 — Age 32

Seven years later: you're done paying.

Age 25 → Age 32

Seven years have passed.

Your career may have changed.

Maybe you're married now.

Maybe there are children.

Maybe the young professional who started the plan barely resembles the person you've become.

But one thing has changed financially:

The paying period is finished.

The Kaiser journey isn't.

This is an important distinction.

Kaiser is 7-pay, but it isn't a seven-year story.

The Blueprint describes the first seven years as the Accumulation Period, followed by an Extended Period from Years 8 through 20.

7 years paying. 20 years to maturity.

And during those years, the plan has another job: life protection.

The historical K100 Blueprint lists ₱450,000 term life insurance for 20 years, subject to its stated age limitation.

So stopping payments doesn't mean the story stops.

It enters another chapter.
Chapter 3 — Ages 32 to 45

Now give the plan time to work.

Years 8 through 20 are different.

You're no longer making the seven annual plan payments.

Meanwhile, unused health benefits can accumulate according to the plan mechanics.

The historical Blueprint's illustration shows the K100 projected fund moving from:

₱42,981at Year 7₱69,072at Year 8₱98,079at Year 9₱130,313at Year 10₱353,180at Year 15₱1,166,169at Year 20

The historical projection assumes 10% compounded annual growth and no withdrawal/use of health benefits. It is an illustration, not an assurance.

That qualification matters.

Because the objective of healthcare isn't to win a contest for the biggest account value.

It's to be there when you need it.

A decision along the way

What if you actually need the healthcare?

Use it.

That's what it's there for.

This journey can go in two directions.

If you need healthcare

The healthcare resources can help you when you need them, subject to the plan's terms and available benefits.

Your eventual accumulated value may therefore be lower.

But that doesn't mean the plan failed.

You used the healthcare for the reason you prepared it.

If you don't need it

Unused benefits have the opportunity to remain in the plan and accumulate.

Either way: You're prepared.

That is more important than maximizing an illustration.

Chapter 4 — Age 45

Twenty years later: maturity.

The 25-year-old is now 45.

The seven-year paying period ended long ago.

Twenty years have now passed since the journey began.

Under the historical K100 illustration:

Projected value at Year 20: ₱1,166,169

assuming the illustrated growth and no use of health benefits.

It's tempting to think: Done. Take the money.

But this is where the Kaiser story becomes particularly interesting.

Year 20 isn't necessarily the finish line.

The Blueprint says the plan is intended to be used after 20 years or more, although healthcare benefits can be used earlier.

At 45, you may still have another 15 or 20 working years ahead of you.

And the years when healthcare is likely to matter most may still be ahead too.

So there is another possibility:

Leave the accumulated value working for its intended long-term purpose.

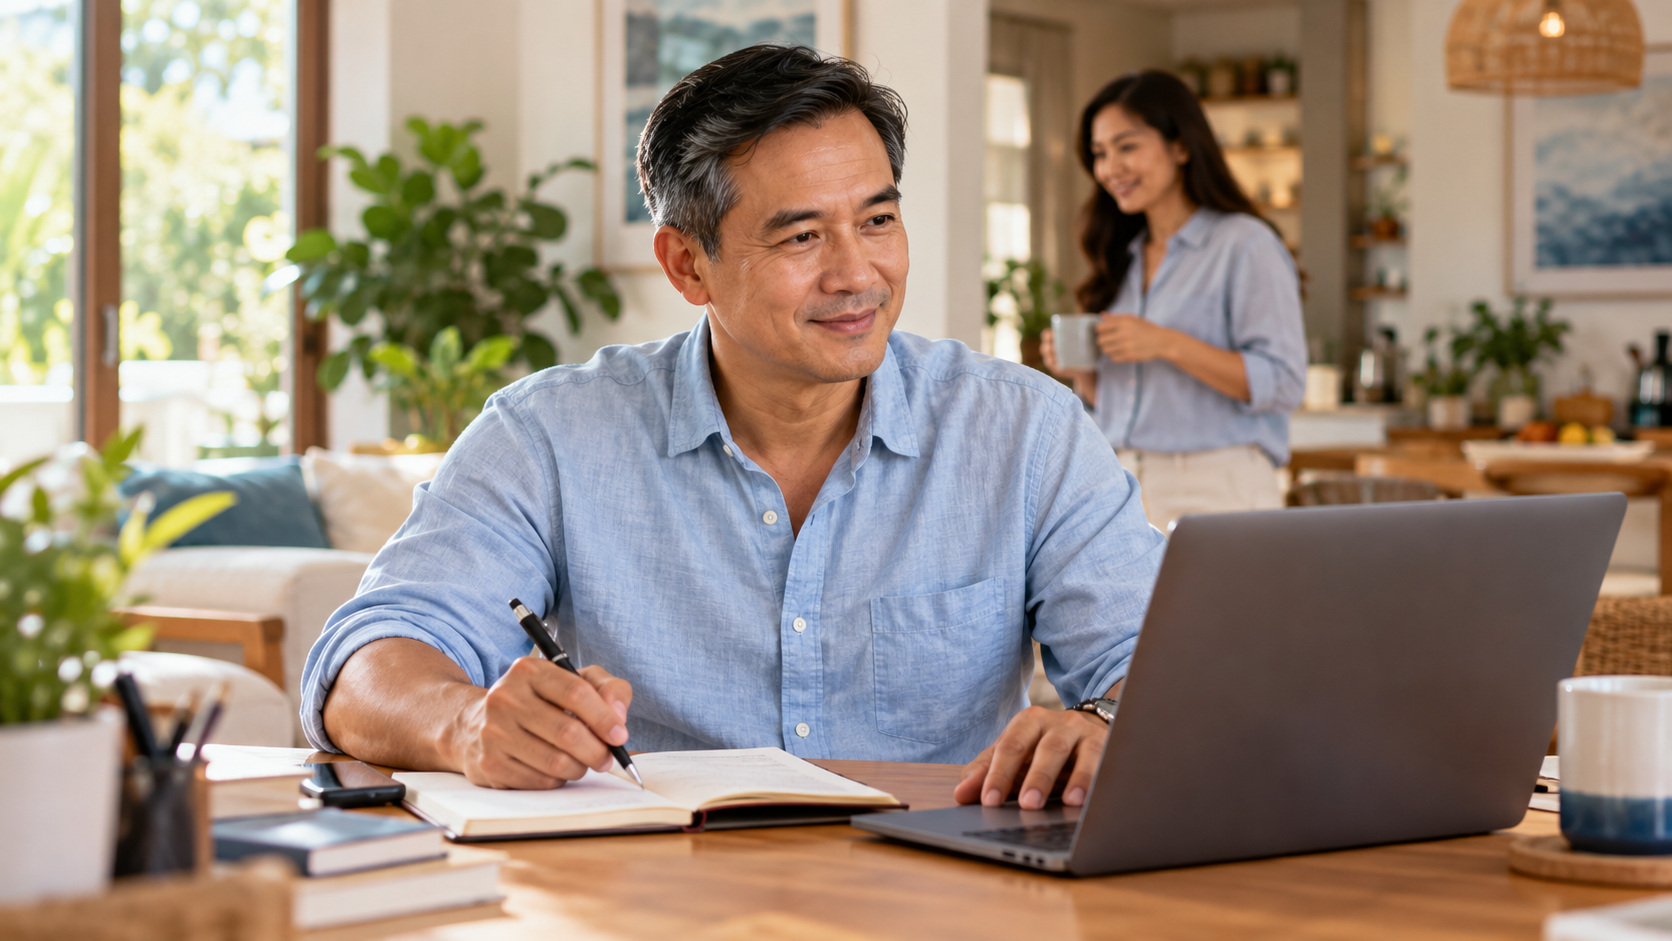
Mature Filipino professional still actively working at a home desk.
Chapter 5 — What happens after maturity?

You don't suddenly stop needing healthcare at Year 20.

Quite the opposite.

At 45, you may still have employer healthcare.

You're probably still earning.

You may still be healthy.

So if you don't need the accumulated healthcare resources yet, why automatically consume them simply because the plan reached maturity?

The historical Blueprint illustrated continued values beyond Year 20:

Time from startAge in this exampleHistorical K100 illustration
20 years45₱1,166,169
25 years50₱1,878,127
30 years55₱3,024,742
35 years60₱4,871,377

These figures come from the historical K100 Blueprint and use its 10% growth illustration; they are not guaranteed results.

And now the original idea starts to make sense.

You didn't prepare long-term healthcare because you expected to need it at 25.

You prepared because someday you might be 60.

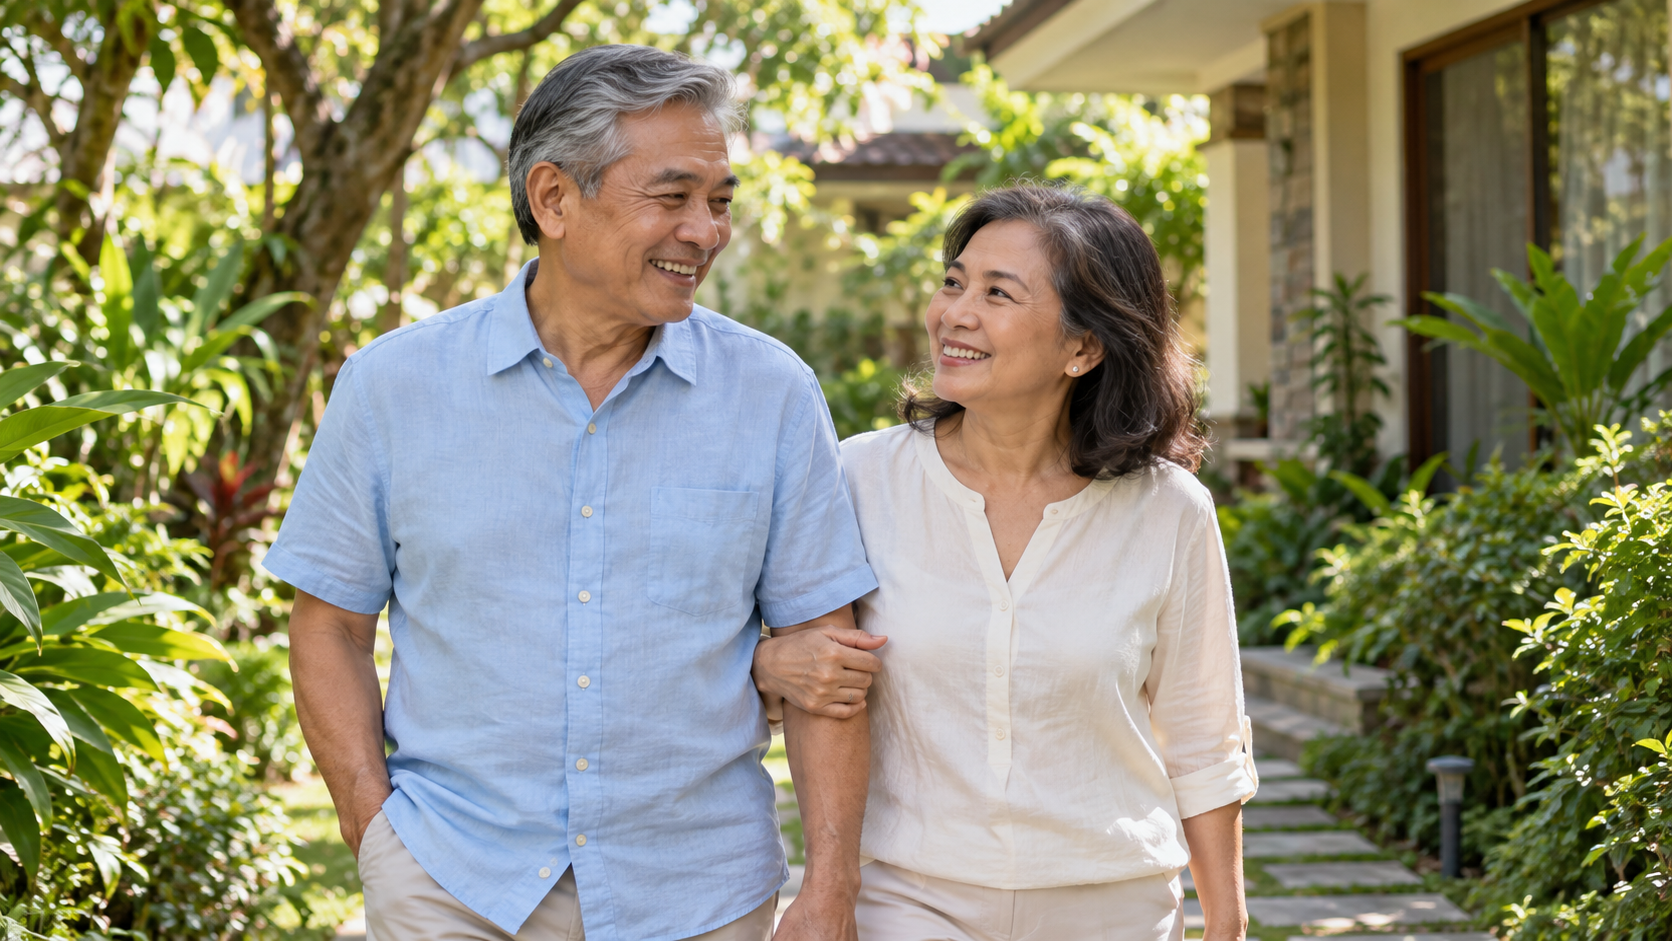
Older Filipino couple walking together in a leafy garden.
Chapter 6 — Age 60

The future you were preparing for has arrived.

Think about the person who started this journey.

At 25: young, healthy and earning.

At 32: finished paying.

At 45: reached the plan's 20-year maturity.

At 60: the person is approaching or entering retirement—and healthcare may now matter much more than it did when the journey began.

Under the historical K100 illustration, preserving the accumulated healthcare value through age 60 produced an illustrated value of approximately:

₱4.87 million

again assuming the historical 10% growth illustration and no use of healthcare benefits.

But ₱4.87 million is not the moral of the story.

The bigger lesson is this:

Long-term healthcare is optimized for long-term healthcare.

You prepared while you were young.

You had healthcare available along the way.

You had life protection during the 20-year period.

And if you remained healthy enough not to consume the healthcare resources, they had time to accumulate toward the years when healthcare could matter even more.

Three possible tomorrows

Three very different futures. One reason to prepare.

Three scenes showing a calm healthcare consultation, a family together at home, and an active older couple.

What if I get sick?

You prepared healthcare resources.

What if I die too soon?

There was life protection during the 20-year period.

What if I live long?

You prepared resources for long-term healthcare.

Whatever Tomorrow Brings.

The real goal

Not the biggest number. Peace of mind.

There's an important danger in showing an illustration like ₱4.87 million.

Someone may think: Then I shouldn't use my Kaiser benefits because I want the money to grow.

That's not the lesson.

If you need healthcare, use it.

That's what healthcare is for.

If you have other appropriate resources available—such as an emergency fund—you can decide which resource makes the most sense to use first.

But healthcare must not be delayed merely to preserve an illustration.

The objective isn't: Die with the largest Kaiser balance possible.

The objective is: Be prepared when healthcare is needed.

And if you remain healthy? Let time keep working for you.

Either way: Enjoy peace of mind.

Your journey will be different

You may not be 25.

You may choose a different Kaiser plan.

You may need healthcare along the way.

Actual rates and accumulated values may differ from historical illustrations.

That's why this page should be treated as a story showing how long-term healthcare planning can work over time, not as a personalized projection.

Your own journey starts with a simpler question:

What would long-term healthcare preparation look like at your age?

Important disclosure: The numerical journey above is based on the historical Kaiser K100 Blueprint and is presented for educational illustration. The Blueprint's projected values assume 10% compounded annual growth and no withdrawals/use of healthcare benefits. Projected values are not guaranteed. Product benefits, eligibility, rates, limitations and current contractual terms should be verified against current Kaiser materials before publication or application. The historical Blueprint is marked confidential; publication permissions and current compliance requirements should be confirmed before any Blueprint-derived figures or wording are published.

Apply the lesson