Education
Save today. Give your children a brighter tomorrow.Build a fund for their college education and the opportunities that come with it.
Education, a better home, travel, business and retirement can take years of work and disciplined saving. The risk is that the person funding the dream may not be there for the entire journey.
Build a fund for their college education and the opportunities that come with it.
Your dream home begins with the discipline to save for it today.
Turn your dream destinations into unforgettable adventures—one peso at a time.
Your future enterprise can start with the money you patiently set aside today.
Build the financial freedom to enjoy a happy, healthy, and prosperous retirement.
The term-insurance component protects the family during the 18-year coverage period. The Premium Deposit Fund provides a separate mechanism for accumulating money toward the goal.
 Protection
Substantial life insurance protection at relatively low term-insurance cost, subject to underwriting and policy terms.
 Growth
The PDF can grow through compounded interest. Projected values depend on actual rates, deposits, withdrawals and insurance costs.
 Safety
The PDF is designed not to go negative, with an interest-rate floor tied to savings-account rates at leading local banks, subject to policy terms.
 Flexibility
The PDF can help pay future premiums and can also be withdrawn for planned goals, subject to policy terms and applicable limits.
This example shows the protection benefits for a 30-year-old.
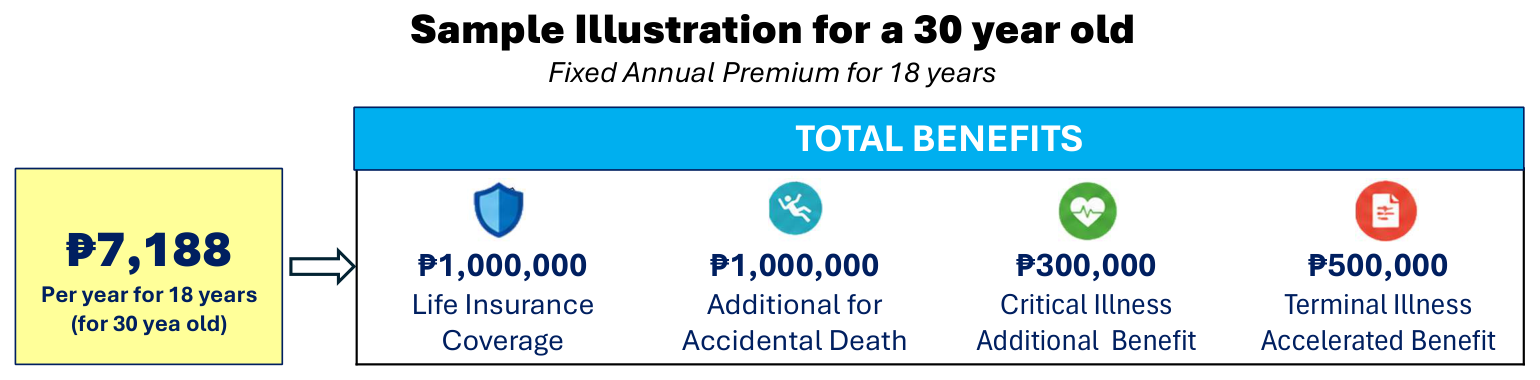
| Fixed annual premium | ₱7,188/year for 18 years |
|---|---|
| Life insurance coverage | ₱1,000,000 |
| Additional accidental death | ₱1,000,000 |
| Critical illness additional benefit | ₱300,000 |
| Terminal illness accelerated benefit | ₱500,000 |
MOST18 is easier to understand when the insurance and PDF are not blended into one vague “investment” story.
Contributions beyond the insurance premium can be allocated to the PDF. This allows a planned annual contribution to do two jobs: pay the protection cost and build the goal fund.
Interest is compounded. Actual rates and future values can vary and are not guaranteed projections.
Withdrawals can fund goals such as education, but withdrawals reduce what remains to compound. The detailed proposal also warns that enough PDF should remain to cover future premiums where the PDF is being used for that purpose.
Provides an additional cash benefit if death is due to a covered accident, subject to policy terms.
If the insured is a minor and the payor dies or becomes totally and permanently disabled, the remaining balance is waived, subject to policy terms.
Critical illness provides an additional 30% of the basic death benefit. Terminal illness accelerates 50% of the death benefit up to ₱500,000, subject to policy terms.
An age-39 example with planned education withdrawals shows how the contribution schedule, withdrawals and assumed rate affect the remaining PDF balance.
The detailed example uses ₱1,000,000 basic life coverage with additional benefits and an annual insurance cost inside the total planned contribution.
Education withdrawals in the illustration run across multiple years. Every withdrawal changes the later PDF balance.
The proposal shows how very different PDF rates can produce very different future balances. Projections should therefore be shown as scenarios, not promises.
It is an unbundled term life insurance product with a Premium Deposit Fund. Treat the insurance protection and PDF accumulation as separate components.
The coverage period is 18 years, subject to policy terms.
Yes. The planning concept includes education, home, business, travel and retirement goals. Withdrawals reduce the amount left to compound.
No. Future values depend on actual rates, contributions, withdrawals and applicable policy costs.
Download the “Big Dreams Take Time” short brochure.

Start with the goal, target date, family protection need and contribution budget.